Freightos Baltic: Transpacific clings to peak highs on pre-holiday rush as Asia–Europe tumble accelerates
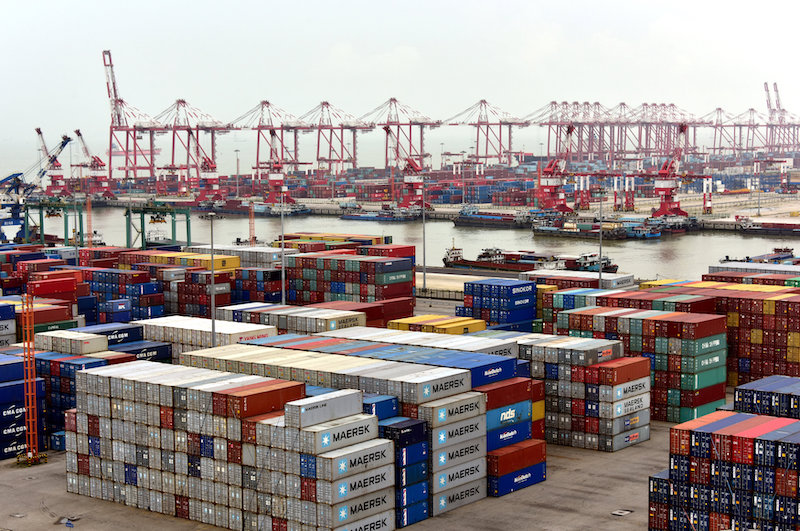
Asia–Europe container freight rates accelerated their downward correction in the week to 23 September 2026 as post-peak demand cooling and expanding Red Sea transits released effective capacity.
|
Route |
Cost (USD/FEU) |
Changes |
|
Updated on 23 September 2026 |
||
|
Asia – US West Coast |
$ 8,102 |
á 4% |
|
Asia – US East Coast |
$ 9,606 |
â 1% |
|
Asia – Northern Europe |
$ 3,702 |
â 15% |
|
Asia – Mediterranean |
$ 3,881 |
â 7% |
Read more on Freightos
Asia–Europe container freight rates accelerated their downward correction in the week to 23 September 2026 as post-peak demand cooling and expanding Red Sea transits released effective capacity, whereas Transpacific corridors hovered near annual peaks amid severe origin hub delays and a pre-Golden Week cargo rush.
According to the Freightos Baltic Index (FBX), Asia–Northern Europe rates posted the sharpest weekly contraction, tumbling 15% to $3,702/FEU—down from July peaks near $6,000/FEU, though remaining roughly $1,000/FEU above pre-peak May baselines. Asia–Mediterranean prices fell 7% to $3,881/FEU, completely unwinding peak-season surcharges to return to late-May levels.
In contrast, Transpacific fundamentals held firm: Asia–US West Coast rates climbed 4% to $8,102/FEU, while Asia–US East Coast rates held broadly flat, edging down 1% to $9,606/FEU.
The pronounced softening on Europe-bound lanes underscores both seasonal volume exhaustion and the steady restoration of shorter Suez Canal transits, which have released vessel capacity back into the market—particularly on Mediterranean strings. Nevertheless, Northern European routes face emerging supply-side friction from destination port congestion, Rhine River draft restrictions, and the looming threat of an indefinite German port strike by the Verdi union in October.
Conversely, the Transpacific market remains structurally underpinned by tight vessel availability. Resilient North American intake and an eleventh-hour push to clear consignments ahead of China's Golden Week holiday have collided with weather-related berth congestion and carrier blank sailings across Far East load ports. While current rates reflect peak-season 2024 pressure rather than pandemic-era extremes—when spot costs exceeded $20,000/FEU with mandatory premium guarantees—tight space continues to delay any broader market correction.
On the policy front, bilateral US-China trade talks ahead of this week’s presidential summit have anchored near-term stability, with markets anticipating an extension of the bilateral tariff truce and the continued suspension of $1 million port call fees on reciprocal vessel tonnage, momentarily tempering immediate supply chain disruption.
Written by: Aiman Haikal